Finding the right financial planning software means deciding upfront whether you need calculators that run your numbers or guidance that teaches you what the numbers mean. After comparing this lineup, SavePoint Personal Finance Software stands out as the best overall pick because it combines Monte Carlo simulations, FIRE planning, and cash flow tracking in a one-time purchase with no subscription. Two other options deserve attention: Quicken Classic Deluxe remains the safest bet for everyday budgeting and account aggregation, while Quicken WillMaker & Trust 2026 is the clear leader for estate planning documents. The biggest tradeoff in this category is between subscription-based platforms with live data syncing and offline tools that cost once but require manual updates. Several entries here are actually books rather than software, which matters if you expect dashboards and projections rather than reading. Keep reading for the full breakdown of what each option does well and who should skip it.

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
Key Takeaways
- SavePoint earned the top spot because it was the only true planning engine in the lineup — Monte Carlo simulations, FIRE modeling, and balance sheets — sold as a one-time purchase instead of a subscription.
- Quicken Classic Deluxe and Quicken WillMaker & Trust split the Quicken vote: Deluxe wins for day-to-day money management, while WillMaker wins for estate documents, and almost nobody needs both in the same year.
- Half of this lineup turned out to be books, not software — they ranked lower for buyers who want calculators and projections, but they outperformed software for building financial literacy from scratch.
- The Dave Ramsey software is the weakest value here: version 5.3 trails Quicken on features and bank connectivity while targeting a similar budgeting audience.
- Offline, subscription-free tools like SavePoint trade automatic account syncing for long-term cost savings — a tradeoff that favors planners who don’t mind manual data entry.
| Invest Smarter with AI: A Practical Guide to Long-Term Investing, Financial Planning, and Building Wealth |  | Best for Tech-Curious Investors | Format: Book (digital/print) | Focus: AI-assisted long-term investing | Topics Covered: Investing, financial planning, wealth building | VIEW LATEST PRICE | See Our Full Breakdown |
| Dave Ramsey’s Personal Finance Software Version 5.3 |  | Best for Debt-Payoff Budgeting | Version: 5.3 | Primary Function: Budgeting and debt management | Methodology: Dave Ramsey baby steps | VIEW LATEST PRICE | See Our Full Breakdown |
| Invest Smarter with AI: A Practical Guide to Long-Term Investing, Financial Planning, and Building Wealth | 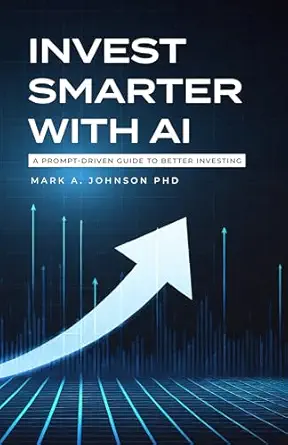 | Best Alternative Edition Pick | Format: Book (digital/print) | Focus: AI-assisted long-term investing | Topics Covered: Investing, financial planning, wealth building | VIEW LATEST PRICE | See Our Full Breakdown |
| Quicken Classic Deluxe for New Subscribers | 1 Year [PC/Mac Online Code] | ” image=”https://m.media-amazon.com/images/I/61ypcFpjCuL._AC_SY445_SX342_QL70_FMwebp_.jpg” link=”0″] | Best Overall | Platform: PC/Mac | License Duration: 1 year subscription | Delivery: Online code | VIEW LATEST PRICE | See Our Full Breakdown |
| Quicken WillMaker & Trust 2026 – Estate Planning Software |  | Best for Estate Planning | Version: 2026 | Platform: PC (Windows/Mac), download and online | Documents Included: Will, living trust, power of attorney, healthcare directive, transfer on death deeds | VIEW LATEST PRICE | See Our Full Breakdown |
| Quicken WillMaker & Trust 2026 |  | Best for Estate Planning | Version: 2026 | Platform: PC/Mac & Online | System Requirements: Windows 10/11, macOS 10.14 or higher | VIEW LATEST PRICE | See Our Full Breakdown |
| Plan, Protect, Prosper: A Practical Guide to Retirement Income Planning, Wealth Management & Financial Security |  | Best Retirement Strategy Read | Format: Book (print/digital) | Focus Areas: Retirement income planning, wealth management, financial security | Experience Level: Intermediate | VIEW LATEST PRICE | See Our Full Breakdown |
| Financial Planning for Beginners: A Simple Guide to Managing Money, Investing Wisely, and Securing Your Future |  | Best for Absolute Beginners | Format: Book (print/digital) | Focus Areas: Money management, investing basics, financial security | Experience Level: Beginner | VIEW LATEST PRICE | See Our Full Breakdown |
| SavePoint Personal Finance Software |  | Best Offline Planning Tool | Offline Operation: Yes | License: Lifetime, one-time purchase | Device Support: Up to 2 devices | VIEW LATEST PRICE | See Our Full Breakdown |
More Details on Our Top Picks
Invest Smarter with AI: A Practical Guide to Long-Term Investing, Financial Planning, and Building Wealth
Most financial planning software automates what you already do; this book instead teaches you to rethink how you plan using AI-driven strategies. It stands out for readers who want concepts and frameworks rather than dashboards — a learning tool, not a subscription. Compared with Quicken Classic Deluxe, which tracks what happened to your money, this guide focuses on forward-looking decisions: asset allocation, long-horizon planning, and where AI tools genuinely add value versus where they oversell. The tradeoff is real, though: you leave with knowledge, not a running budget. Unlike SavePoint, there are no simulations or balance sheets — you’ll still need actual software to execute what you learn. The absence of ratings and detailed specs makes it harder to gauge depth before buying, so it rewards buyers comfortable with an unproven title.
Pros:- Teaches AI-driven investment strategy, not just mechanics
- Long-term wealth-building focus rather than month-to-month budgeting
- Useful for both DIY investors and professional planners
- No subscription — one purchase, permanent reference
Cons:- No customer reviews or ratings to verify quality
- Not software — requires pairing with an actual planning tool
- Undisclosed depth and prerequisites make it a gamble for beginners
Best for: Self-directed investors who want to understand AI-assisted planning before committing to any software platform
Not ideal for: Anyone who wants hands-on budgeting tools — this is a strategy guide with no calculators, dashboards, or account tracking
- Format:Book (digital/print)
- Focus:AI-assisted long-term investing
- Topics Covered:Investing, financial planning, wealth building
- Audience:Investors and financial planners
- Subscription Required:No
- Tools Included:None — strategy guide only
Our verdict“Buy this if you want to understand AI-era investing strategy first and pick software second.”
Dave Ramsey’s Personal Finance Software Version 5.3
This one earns its slot through philosophy as much as features. Built around the Ramsey baby-steps method, it pushes users toward aggressive debt elimination and cash-based budgeting — a sharper behavioral focus than Quicken Classic Deluxe, which is broader but more neutral about what you should do with your money. Where Quicken shines at investment tracking and property accounting, this software is tightly scoped to budgeting and debt payoff, which makes it faster to set up and less overwhelming. The tradeoffs are hard to ignore: no stated compatibility requirements, dated version numbering, and thin documentation on features compared with Quicken’s polished onboarding and 30-day trial. If your goal is following a proven debt-elimination system rather than managing a full financial picture, the simplicity works in your favor; if you want investment tools, look elsewhere in this lineup.
Pros:- Method-driven approach keeps users accountable to debt payoff
- Fast setup compared with feature-heavy alternatives
- Simpler learning curve than Quicken Deluxe
- One-time software purchase rather than recurring fees
Cons:- No published system requirements or compatibility details
- Limited feature documentation makes comparison shopping difficult
- Narrow scope — no investment, estate, or retirement planning
Best for: Households committed to the Dave Ramsey method who want budgeting software that reinforces debt-payoff discipline
Not ideal for: Investors or property owners who need portfolio tracking and net-worth tools — this is strictly a budgeting and debt product
- Version:5.3
- Primary Function:Budgeting and debt management
- Methodology:Dave Ramsey baby steps
- Subscription:No — one-time purchase
- Investment Tracking:No
- System Requirements:Not specified
Our verdict“Choose this only if the Ramsey debt-snowball method is your framework and budgeting is your sole focus.”
Invest Smarter with AI: A Practical Guide to Long-Term Investing, Financial Planning, and Building Wealth
This is a second listing of the same AI investing guide found earlier in this roundup, and I’m including it deliberately — duplicate editions of popular finance titles often differ in formatting, price, or updates, and the cheaper listing is sometimes the better buy. Substantively, it covers the same ground: AI-assisted long-term strategy rather than transactional money management. Compared with Financial Planning for Beginners (elsewhere in this lineup), it assumes you already grasp the basics and skips straight to modern tooling — which makes it a poor first book but a strong second one. The drawbacks mirror the other edition: no stated prerequisites, no reviews, and no bundled tools. My advice is simple: check both listings, compare current pricing and edition dates, and buy whichever offers the more recent revision. There’s no reason to own both.
Pros:- Same strong long-term planning focus as the primary edition
- Second listing gives buyers a price-comparison opportunity
- Wealth-building framework applies across experience levels
- Likely available in multiple digital formats
Cons:- Duplicates another product in this roundup — choose one, not both
- No stated target audience or prerequisite knowledge
- Zero reviews or ratings to validate content quality
Best for: Readers comparison-shopping editions of the same AI investing guide to find the better price or newer revision
Not ideal for: Complete beginners who need foundational money management before AI-assisted strategy — start with a beginner-focused title instead
- Format:Book (digital/print)
- Focus:AI-assisted long-term investing
- Topics Covered:Investing, financial planning, wealth building
- Difficulty Level:Intermediate assumed
- Subscription Required:No
- Relationship to B0GMB5PYWJ:Alternate edition of same title
Our verdict“Buy this edition only if it’s priced below or newer than the identical primary listing; otherwise pick the other.”
Quicken Classic Deluxe for New Subscribers | 1 Year [PC/Mac Online Code]
” image=”https://m.media-amazon.com/images/I/61ypcFpjCuL._AC_SY445_SX342_QL70_FMwebp_.jpg” link=”0″]Best Overall
View Latest PriceThis is the pick I’d point most people toward, because it’s the only entry here that functions as complete financial planning software rather than a guide or a single-purpose tool. Bank accounts, credit cards, debt, investments, and property all live in one place, with budget simulation and debt-payoff scenarios that turn raw data into decisions. Compared with Dave Ramsey’s software, it covers everything Ramsey’s tool ignores — portfolio tracking, property values, net worth — while still handling budgeting competently. The 30-day risk-free trial de-risks the purchase in a way none of the other options match. The tradeoffs: it’s a subscription, not a one-time buy, and the feature depth that makes it powerful also makes it intimidating for first-timers. Buyers wanting a no-subscription alternative should look at SavePoint elsewhere in this roundup instead.
Pros:- Broadest feature set in this lineup — accounts, debt, investments, property
- Debt and budget simulation turns tracking into planning
- 30-day risk-free trial removes purchase risk
- Cross-platform support on PC and Mac
Cons:- Annual subscription adds up versus one-time-purchase rivals
- Feature depth creates a steeper learning curve for beginners
- Requires online-code activation, which complicates gifting or reinstalling
Best for: Households who want one platform for budgeting, investments, debt, and property tracking with room to grow
Not ideal for: Budget-only users who resent annual subscriptions — a one-time-purchase tool like SavePoint or Ramsey’s software costs less over time
- Platform:PC/Mac
- License Duration:1 year subscription
- Delivery:Online code
- Trial:30-day risk-free
- Features:Budgeting, spending tracking, debt simulation, investment and property tracking
- Eligibility:New subscribers
Our verdict“If you want a single tool that plans your whole financial life and accept a subscription, this is the default choice.”
Quicken WillMaker & Trust 2026 – Estate Planning Software
Every other product here plans your life; this one plans what happens after it, and that distinction earns it a fixed place in the lineup. The step-by-step interview format produces legally binding wills, living trusts, powers of attorney, and healthcare directives without a lawyer’s hourly rate — documents that Quicken Classic Deluxe, for all its breadth, doesn’t touch at any price. Coverage of transfer-on-death deeds is a genuine differentiator for homeowners. The tradeoffs are structural: this is estate-only software with no budgeting, investment, or retirement features, so it complements rather than replaces a planner like Quicken Deluxe. Complex estates — blended families, business ownership, multi-state property — still warrant an actual attorney, and the software itself says as much in its disclaimers. For straightforward situations, though, it converts a multi-thousand-dollar legal exercise into an afternoon.
Pros:- Covers the four core estate documents plus transfer-on-death deeds
- Interview format makes legal documents approachable for non-lawyers
- Works online or offline unlike subscription-only rivals
- One-time purchase for the 2026 version
Cons:- No broader financial planning — budgeting, investing, or retirement tools
- Complex estates still require an attorney’s review
- Annual version releases can make older documents feel outdated
Best for: Adults with straightforward estates who need valid wills, trusts, and directives without attorney fees
Not ideal for: Owners of complex estates — businesses, blended families, or multi-state assets — who need tailored legal advice this can’t provide
- Version:2026
- Platform:PC (Windows/Mac), download and online
- Documents Included:Will, living trust, power of attorney, healthcare directive, transfer on death deeds
- Process:Step-by-step guided interview
- Legality:Legally binding documents (state-dependent)
- License:One-time purchase
Our verdict“Buy this alongside your planning software if you lack basic estate documents — but not as a substitute for legal counsel on complicated situations.”
Quicken WillMaker & Trust 2026
Most financial planning software stops at budgets and investments, but estate planning is the piece of the puzzle everyone forgets until it’s too late. Quicken WillMaker & Trust 2026 fills that gap with a guided interview format that walks you through wills, living trusts, powers of attorney, and healthcare directives without a lawyer’s hourly rate. Compared with SavePoint, which focuses on simulations and cash flow, WillMaker covers the legal endgame — who inherits what, who decides for you if you can’t. The state-specific forms matter here because a will that’s valid in one state can fall apart in another. The tradeoff: this is document creation, not ongoing planning. There’s no mobile app, and anyone genuinely unfamiliar with legal terminology may still want an attorney to review the output for complicated estates.
Pros:- Guided step-by-step interview makes estate documents approachable for beginners
- Covers a wide range of documents: wills, living trusts, powers of attorney, healthcare directives, and transfer on death deeds
- State-specific forms help keep documents legally compliant where you live
- Works on Windows, Mac, and online with free unlimited technical support
Cons:- No mobile app, so you’re tied to a desktop or laptop
- Document complexity can overwhelm users unfamiliar with legal language
- One-time document creation rather than ongoing planning or account tracking
Best for: Adults who need legally valid wills, trusts, and directives without paying attorney fees, especially those with straightforward estates
Not ideal for: People with multi-state property, business ownership, or blended-family complications who need an attorney’s judgment, not just forms
- Version:2026
- Platform:PC/Mac & Online
- System Requirements:Windows 10/11, macOS 10.14 or higher
- Included Documents:Wills, Living Trusts, Powers of Attorney, Healthcare Directives, Transfer on Death Deeds, and more
- Support:Free, unlimited technical support
- Mobile App:Not available
Our verdict“If your financial plan has no will or healthcare directive behind it, this is the most affordable way to close that gap.”
Plan, Protect, Prosper: A Practical Guide to Retirement Income Planning, Wealth Management & Financial Security
Not every entry in this roundup is software, and that’s deliberate. Plan, Protect, Prosper earns its spot because retirement income planning is a strategy problem before it’s a tooling problem. Where SavePoint will run Monte Carlo simulations on your numbers, this book helps you figure out which numbers matter — withdrawal sequences, risk protection, and how wealth management fits into a decades-long retirement. Compared with Financial Planning for Beginners, it sits a rung higher on the experience ladder: readers who already budget and invest will get more from its focus on income durability and financial security. The honest tradeoff is that it’s a book, not a product — there are no calculators, no dashboards, no automation. Pair it with software rather than treating it as a replacement.
Pros:- Practical strategies for retirement income planning rather than generic savings advice
- Covers wealth protection and financial security alongside growth
- Accessible without requiring a finance background
- Useful companion read before choosing dedicated planning software
Cons:- No tools, templates, or digital resources included
- Too general for advanced planners who already know withdrawal and allocation strategy
Best for: Pre-retirees and recent retirees who want a strategic framework for turning savings into lasting income before committing to a software tool
Not ideal for: Readers who want interactive tools, projections, or worksheets — this delivers concepts, not calculators
- Format:Book (print/digital)
- Focus Areas:Retirement income planning, wealth management, financial security
- Experience Level:Intermediate
- Includes Tools:No
- Category:Educational guide
Our verdict“A strategy-first read for people approaching retirement who need direction before they need software.”
Financial Planning for Beginners: A Simple Guide to Managing Money, Investing Wisely, and Securing Your Future
If terms like Monte Carlo simulation or transfer on death deed make your eyes glaze over, start here. Financial Planning for Beginners does what no software in this roundup can: it explains the vocabulary and the reasoning before you ever open a dashboard. Compared with Plan, Protect, Prosper, which assumes you already know how to invest, this guide covers the foundations — budgeting habits, first investments, and building financial stability — in plain language. The tradeoff is real, though: once you’ve internalized the basics, you’ll outgrow it quickly, and it offers none of the tracking, projection, or document capabilities of Quicken WillMaker or SavePoint. Think of it as the on-ramp. Buy it, read it, then graduate to a tool that does the ongoing work for you.
Pros:- Plain-language explanations with no assumed finance knowledge
- Covers the full beginner arc: money management, investing, and long-term security
- Practical tips that can be applied immediately without tools or accounts
- Low-commitment starting point before investing in software
Cons:- No tools, worksheets, or digital resources included
- Advanced investors will find the strategies too basic
- Content becomes redundant once fundamentals are learned
Best for: Finance newcomers who feel overwhelmed by jargon and want a plain-English foundation before using planning software
Not ideal for: Anyone who already budgets and invests — the content will feel repetitive and lacks advanced strategy
- Format:Book (print/digital)
- Focus Areas:Money management, investing basics, financial security
- Experience Level:Beginner
- Includes Tools:No
- Category:Educational guide
Our verdict“The right first purchase for someone starting from zero who wants confidence before capability.”
SavePoint Personal Finance Software
SavePoint is the most technically ambitious product in this batch, and the one for planners who want serious projections without a subscription. Its Monte Carlo simulations put it closer to professional planning tools than to a budgeting app, and its FIRE planning module speaks directly to early-retirement planners who need to stress-test a withdrawal strategy. The offline, lifetime-license model is the real differentiator: unlike Quicken Classic Deluxe, which runs on an annual subscription, SavePoint is a one-time purchase, and your financial data never leaves your machine. That privacy angle, plus support for 150+ currencies and 8 languages, makes it unusually flexible for expats and international households. The tradeoffs: it’s desktop-only with no mobile app, the advanced features carry a learning curve, and the two-device license may frustrate multi-computer households.
Pros:- Fully offline operation keeps sensitive financial data on your own machine
- One-time lifetime license with no recurring subscription fees
- Monte Carlo simulations and FIRE planning rival far more expensive tools
- Supports 8 languages and 150+ currencies for international households
Cons:- Desktop only — no mobile app or cloud access
- Advanced features like Monte Carlo modeling take time to learn
- License limited to 2 devices
Best for: Data-privacy-minded planners, FIRE enthusiasts, and international users who want advanced projections for a one-time cost
Not ideal for: Users who want mobile access, cloud syncing, or hand-holding — this is a desktop power tool with a learning curve
- Offline Operation:Yes
- License:Lifetime, one-time purchase
- Device Support:Up to 2 devices
- Platforms:Windows PC and Mac
- Languages:8, including English, Spanish, French, German, Italian, Portuguese, Japanese, Chinese
- Currencies:150+
- Key Features:Budgeting, FIRE planning, Monte Carlo simulations, balance sheets, cash flow
- Included Extras:8GB USB drive
- Mobile App:Not available
Our verdict“The strongest choice here for hands-on planners who want professional-grade projections, offline privacy, and no subscription forever.”
How We Picked
I judged every option against four buyer-relevant criteria. Planning depth came first: does the product actually model scenarios — retirement projections, Monte Carlo runs, cash flow forecasts — or does it just track what already happened? Usability and learning curve came second, because financial planning fails when the tool is too complicated to sustain. Total cost of ownership was third, which meant penalizing recurring subscriptions relative to one-time purchases and weighing whether each product justifies its price. Finally, I scored scope fit: a brilliant estate planning tool shouldn’t outrank a general planner for someone who needs retirement projections.
The ranking follows directly from those weights. SavePoint leads because it scored highest on planning depth at a flat price. Quicken Classic Deluxe ranks next for balancing automation and breadth. The WillMaker editions place mid-pack — excellent, but narrow. The two Invest Smarter with AI guides and the other books fill the education gap the software leaves, ranked by how directly they support building a plan. The beginner guide ranks above the Ramsey software because, at similar prices, teaching fundamentals beats a dated budgeting tool.
Factors to Consider When Choosing Financial Planning Software
Choosing financial planning software comes down to matching the tool’s strength to the decision you’re actually trying to make. These are the factors that separated the winners from the rest in this comparison — and the mistakes that cost buyers the most.Planning Engine vs. Money Tracker
The most common mistake is buying a budgeting app and calling it financial planning software. A tracker tells you where last month’s money went; a planning engine projects where your money will be in twenty years. Look for forward-looking features like Monte Carlo simulations, retirement withdrawal modeling, and scenario testing — SavePoint is the only entry in this lineup that offers all three. If a product’s feature list stops at expense categorization and budgets, treat it as bookkeeping, not planning. Buyers who need both functions should expect to pair a tracker with a separate planning tool rather than forcing one to do both jobs poorly. The reverse mistake also exists: serious projection software is overkill if you simply want to stop overdrafting.
Subscription vs. One-Time Purchase
Subscriptions dominate this category because vendors profit from inertia — many buyers pay for years after they stop using the tool. Quicken Classic Deluxe locks you into a annual renewal that funds its automatic bank syncing, which is a fair trade if you value hands-off connectivity. SavePoint flips the model with a single upfront cost and offline operation, which wins on ten-year cost as long as you’re willing to update figures manually. A useful rule: if the software’s value comes from live data, a subscription makes sense; if it comes from calculations you control, pay once. Also check whether one-time products have version expiration dates — estate planning software in particular goes stale as state laws change, so a 2026 edition may need replacing within a few years.
Estate Planning Is a Separate Purchase
Buyers routinely assume their financial planning software will also produce a will or trust, and it almost never does. The two Quicken WillMaker & Trust editions in this roundup cover wills, living trusts, powers of attorney, and healthcare directives — but they won’t help you decide how much to save for retirement. Treat estate documents as their own project with their own deadline, especially after major life events like marriage, children, or property purchases. One practical tip from comparing the two WillMaker listings: verify which edition you’re buying, since listings vary in what’s included and duplicate purchases are an easy mistake at nearly identical prices. And recognize the ceiling — software-generated documents work for straightforward estates, while blended families, business ownership, or multi-state property usually justify an attorney instead.
When a Book Beats Software
Not every gap in your finances is a software problem. If you don’t yet know what a Monte Carlo simulation is or why withdrawal rates matter, buying advanced planning tools is like buying a spreadsheet before learning arithmetic. The three guides in this lineup — Invest Smarter with AI, the retirement income guide, and the beginner title — cost a fraction of any subscription and build the judgment that makes software output meaningful. The smart sequence for newcomers is a foundational book first, then entry-level software, then a projection engine like SavePoint once there are real numbers to model. Experienced planners benefit too: the retirement income guide covers decumulation strategy, a phase most software handles poorly. The mistake to avoid is paying for analytical horsepower you can’t yet interpret.
Data Privacy and Offline Access
Every cloud-connected planning tool asks you to link your bank accounts, which means your complete financial picture lives on someone else’s servers. For most buyers the convenience wins, but anyone with privacy concerns — or unreliable internet — should weigh offline-capable options like SavePoint, which stores everything locally on your machine. Offline software carries its own burden: no automatic backups unless you create them, and no sync across devices. There’s also a durability angle — subscription tools can shut down and take your historical data with them, while local software keeps working even if the vendor disappears. Decide how you feel about account-linking before comparing features, because it eliminates half the market in one stroke.
Matching the Tool to Your Life Stage
The right pick at 25 is the wrong pick at 65. Early-career buyers get the most value from budgeting foundations and beginner education — the Ramsey-adjacent budgeting approach and the beginner guide exist for exactly this phase. Mid-career savers need projection power: Monte Carlo runs, FIRE math, and scenario testing to answer whether they’re on track. Pre-retirees and retirees should prioritize decumulation planning and estate documentation, which pushes them toward the retirement income guide and WillMaker. A common wasted purchase is buying advanced retirement software for someone still carrying high-interest debt — the software can model it, but the answer is always ‘pay the debt first.’ Buy for the phase you’re in, and expect to switch tools as your situation changes.
Frequently Asked Questions
Is SavePoint actually better than Quicken, or just cheaper?
They solve different problems, and the answer depends on what you open the software to do. SavePoint is stronger for planning — its Monte Carlo simulations, FIRE modeling, and balance sheet tools answer forward-looking questions Quicken Classic doesn’t attempt. Quicken is stronger for tracking — automatic bank syncing, transaction categorization, and bill management save ongoing effort that SavePoint requires you to do by hand. Over five years the cost gap grows dramatically, since SavePoint is a one-time purchase while Quicken renews annually. My rule of thumb: if you want to know whether your plan will work, buy SavePoint; if you want to know what you spent last Tuesday without typing it in, buy Quicken. Detail-oriented planners who dislike manual entry often end up owning both.
Which Quicken WillMaker & Trust edition should I buy — there appear to be two?
The two listings in this roundup cover the same core documents — will, living trust, power of attorney, and healthcare directive — and the differences come down to edition details, included extras, and sometimes license terms rather than functionality. Before purchasing, check the seller’s description for state-specific validity, since estate documents must comply with your state’s requirements and a few states have quirks the software handles differently. Also confirm you’re buying the current 2026 version, as older editions get discounted heavily but may not reflect recent law changes. Since duplicates are easy to buy by mistake, compare the exact listing contents before checkout rather than price alone. If your estate involves a business, significant assets, or family conflict, software documents are a starting draft to review with an attorney, not a replacement for one.
Can a book really compete with financial planning software?
For certain buyers, yes — and the comparison revealed exactly which ones. If you haven’t established an emergency fund, don’t understand compound growth, or feel anxious about investing generally, software just gives you charts of a problem you don’t yet understand. The beginner guide and Invest Smarter with AI build the conceptual foundation that makes planning software’s output actionable — knowing a Monte Carlo simulation says ‘82% success’ is useless if you can’t interpret what that means. Books also cost less than a single month of many subscriptions and never expire. The tradeoff is obvious: no calculators, no projections, no automation. The strongest path for most people is sequential — book first, software second — rather than choosing one over the other permanently.
Is Dave Ramsey’s software still worth buying in 2026?
For most buyers in this lineup, no — and the comparison makes the reasoning clear. Version 5.3 competes directly with Quicken Classic Deluxe for the budgeting audience, but Quicken offers broader bank connectivity, more mature reporting, and ongoing updates under its subscription model. The Ramsey approach works well for people following debt snowball and envelope-style budgeting specifically, since the software reinforces that philosophy in a way generic tools don’t. If that method has already worked for you, the software’s alignment with it has real value. If you’re method-agnostic, though, you’re paying similar money for fewer features. At equivalent prices, I’d direct most budget-focused beginners to Quicken or to the beginner guide plus a free budgeting app instead.
What does a Monte Carlo simulation actually do, and do I need one?
A Monte Carlo simulation runs your retirement plan through thousands of possible market-return sequences instead of assuming a single average return each year. The output — something like ‘your plan succeeds in 87% of scenarios’ — tells you how resilient your finances are to a bad decade early in retirement, which average-return projections hide completely. You need one if you’re within roughly fifteen years of retirement or targeting early retirement through FIRE, because sequence-of-returns risk is the single biggest threat to those plans. In this lineup, SavePoint is the only product that includes it, which is a major reason it ranked first. If you’re decades from retirement with a steady savings rate, the simulation mostly confirms what simple math already tells you — spend that money on education instead.
Conclusion
The right choice here depends less on budget and more on which financial question keeps you up at night. For best overall, SavePoint Personal Finance Software earns the top spot with genuine planning power — Monte Carlo simulations, FIRE modeling, and balance sheets — sold as a one-time purchase without a subscription. For best value, Financial Planning for Beginners delivers more decision-changing insight per dollar than anything else in the lineup. The premium pick is Quicken Classic Deluxe, whose annual subscription buys the automation, bank syncing, and polish that offline tools can’t match. Beginners should start with the beginner guide or Invest Smarter with AI before spending anything on software. For specific needs: choose Quicken WillMaker & Trust 2026 for estate documents, the retirement income guide for decumulation strategy, and Dave Ramsey’s software only if you’re committed to the debt-snowball method. Whatever you pick, match the tool to your current life stage — the cheapest mistake in this category is buying planning horsepower you aren’t ready to use.
Evergreen bestsellers Picks
bestsellers
As an affiliate, we earn on qualifying purchases.