
Financial planning software ranges from simple budgeting tools to full retirement simulators, and the right choice depends on whether you’re managing daily spending or mapping out decades of future cash flow. SavePoint Personal Finance Software earns my top spot because it combines budgeting, FIRE planning, and Monte Carlo simulations in one offline package with no subscription. Quicken Classic Deluxe is the strongest pick for people who want bank connectivity and day-to-day transaction management, while the Retirement Planning Toolkit Deluxe 2.0 stands out for focused retirement projections. The main tradeoff in this category is subscription versus one-time purchase, plus the gap between living-document planners and tools that need ongoing data feeds. Read on for the full breakdown of what each option does well and who should skip it.
Prime for Young Adults — start your free trial
Fast free delivery, streaming and member deals for eligible 18–24 year olds.
Try it freeAs an affiliate, we earn on qualifying purchases.
Key Takeaways
- SavePoint separated itself from the pack by being the only option that handles budgeting, FIRE planning, and Monte Carlo simulations offline with no recurring fees.
- Two of the seven products (Ramsey 5.3 and Financial Peace) overlap heavily, differing mainly in interface and included extras rather than core capability.
- Quicken WillMaker & Trust is the lone estate planning tool here — it solves a different problem than cash flow planning and shouldn’t be compared on the same axis.
- Retirement Planning Toolkit 2.0 improves on version 1.0 enough that buying the older edition only makes sense at a steep discount.
- Quicken Classic Deluxe is the only pick requiring an annual subscription, which pays off only if you value automatic bank downloads.
- Most of these tools are offline-first, meaning users who want live account syncing have far fewer options in this lineup than expected.
| Dave Ramsey’s Personal Finance Software Version 5.3 |  | Best for Debt-Payoff Beginners | Focus: Budgeting and debt payoff | Methodology: Dave Ramsey baby-steps framework | Skill Level: Beginner | VIEW LATEST PRICE | See Our Full Breakdown |
| Quicken WillMaker & Trust 2026 – Estate Planning Software |  | Best for Estate Planning | Platform: PC download and online | Documents Included: Will, living trust, healthcare directive, power of attorney, transfer on death deeds | Legal Binding: Yes | VIEW LATEST PRICE | See Our Full Breakdown |
| SavePoint Personal Finance Software |  | Best Overall for Serious Planners | Data Storage: Offline, local-only | License: Lifetime, no subscriptions | Platforms: Windows PC and Mac | VIEW LATEST PRICE | See Our Full Breakdown |
| Financial Peace Personal Finance Software | 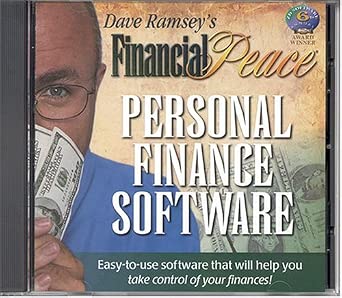 | Best Value for Money-Habit Building | Focus: Budgeting, expense tracking, financial literacy | Skill Level: Beginner to intermediate | Core Tools: Budgets, expense tracking, planning worksheets | VIEW LATEST PRICE | See Our Full Breakdown |
| Retirement Planning Toolkit Deluxe 2.0 [PC Download] | ” image=”https://m.media-amazon.com/images/I/61RfTzIpaTL._AC_SY445_SX342_QL70_FMwebp_.jpg” link=”0″] | Best for Retirement-Focused Planning | Calculators: 19 | Worksheets: Included | Checklists: Included | VIEW LATEST PRICE | See Our Full Breakdown |
| Quicken Classic Deluxe for New Subscribers – 1 Year [PC/Mac Online Code] | ” image=”https://m.media-amazon.com/images/I/61ypcFpjCuL._AC_SY445_SX342_QL70_FMwebp_.jpg” link=”0″] | Best All-in-One Money Manager | Platform: PC/Mac | Duration: 1 Year subscription | Format: Online code | VIEW LATEST PRICE | See Our Full Breakdown |
| Retirement Planning Toolkit Deluxe 1.0 [Download] | ” image=”https://m.media-amazon.com/images/I/51kEf6q-b+L._AC_SY445_SX342_QL70_ML2_.jpg” link=”0″] | Best for Retirement-Focused Planning | Calculators Included: 19 | Calculator Types: Retirement, investment, loan, mortgage | Planning Tools: Checklists and worksheets | VIEW LATEST PRICE | See Our Full Breakdown |
More Details on Our Top Picks
Dave Ramsey’s Personal Finance Software Version 5.3
Dave Ramsey’s Personal Finance Software earns its spot as the friendliest entry point for anyone drowning in debt and allergic to spreadsheets. Where SavePoint assumes you already know what a Monte Carlo simulation is, this option strips financial planning down to Ramsey’s signature baby-steps framework: budget first, attack debt second, build wealth third. That structure is genuinely useful for beginners who need a philosophy, not just a dashboard.
The tradeoff is depth. Compared with the Retirement Planning Toolkit Deluxe 2.0 and its 19 dedicated calculators, this software feels thin on long-horizon planning, and the sparse documentation makes it hard to evaluate before committing. If your goal is a behavioral money reset rather than investment modeling, though, this pick makes the most sense.
Pros:- Simple, guided interface that beginners can set up quickly
- Built around a proven debt-elimination methodology
- Improves budgeting habits through structured discipline
- Low-friction onboarding compared with tool-heavy alternatives
Cons:- Feature documentation is vague, making pre-purchase evaluation difficult
- No advanced planning tools like simulations or investment modeling
- Dated feature set compared with modern offline suites like SavePoint
Best for: Debt-laden beginners and Ramsey-method followers who want guided budgeting over raw analytics
Not ideal for: Analytical planners who need retirement projections, simulations, or multi-currency support
- Focus:Budgeting and debt payoff
- Methodology:Dave Ramsey baby-steps framework
- Skill Level:Beginner
- Setup:Quick setup process
- Advanced Planning:Not included
- Version:5.3
Our verdict“Choose this if you want a motivational, debt-first money system rather than a numbers-heavy planning engine.”
Quicken WillMaker & Trust 2026 – Estate Planning Software
Nobody else in this lineup touches what Quicken WillMaker & Trust 2026 does. While SavePoint and the Retirement Planning Toolkit help you grow and protect wealth, this one decides what happens to it after you’re gone — wills, living trusts, powers of attorney, and healthcare directives, all generated through a step-by-step interview format that translates legalese into plain questions.
At a fraction of an attorney’s fee, it’s a strong value for straightforward estates, and you can revise documents as life changes. The catch: it leans on you to know when your situation is not straightforward. Blended families, business ownership, or sizable taxable estates still warrant a lawyer, and the Windows-only desktop version frustrates Mac households.
Pros:- Step-by-step interview format makes legal documents approachable
- Covers wills, trusts, POAs, and healthcare directives in one package
- Far cheaper than a lawyer for standard estate needs
- Documents can be updated as circumstances change
Cons:- Desktop version requires Windows; Mac users limited to online access
- Not suitable for complicated estate situations without professional review
Best for: Individuals and couples with straightforward estates who want legally binding documents without attorney fees
Not ideal for: Owners of complex estates — businesses, blended families, or significant assets — who need customized legal counsel
- Platform:PC download and online
- Documents Included:Will, living trust, healthcare directive, power of attorney, transfer on death deeds
- Legal Binding:Yes
- Process:Guided step-by-step interview
- Updates:Editable as circumstances change
- Version:2026
Our verdict“A cost-effective estate-planning solution for simple estates — skip it and hire a lawyer if your situation involves business or blended-family complexity.”
SavePoint Personal Finance Software
SavePoint takes the top slot because it’s the only product here that treats financial planning as an actual discipline rather than a budgeting chore. Monte Carlo simulations, FIRE planning, balance sheets, and cash-flow analysis put it in a different class from Dave Ramsey’s software, and the lifetime license with zero subscriptions undercuts Quicken Classic Deluxe’s annual-fee model over any multi-year horizon.
The offline, local-only architecture is its defining tradeoff: your data never touches a cloud, which privacy-minded buyers will love — but there’s no automatic backup and no mobile app, so you’re responsible for your own redundancy. A steeper learning curve on the analytical tools means casual budgeters may never touch half of what they paid for. For planners who want depth and data ownership, nothing else in this roundup compares.
Pros:- Monte Carlo simulations and FIRE planning rival far pricier tools
- One-time purchase with lifetime updates beats subscription rivals on cost
- Offline local storage keeps sensitive data private
- 8 languages and 150+ currencies suit internationally-minded households
Cons:- No mobile app and no cloud backup — manual data management required
- Advanced features carry a real learning curve for beginners
Best for: Data-privacy-focused planners and FIRE enthusiasts who want advanced analytics without recurring fees
Not ideal for: Casual budgeters who want mobile access, cloud sync, and a gentle learning curve
- Data Storage:Offline, local-only
- License:Lifetime, no subscriptions
- Platforms:Windows PC and Mac
- Languages:8 including English, Spanish, French, German
- Currency Support:150+ currencies
- Advanced Tools:Monte Carlo simulations, FIRE planning, balance sheets, cash flow
- Includes:8GB USB drive
Our verdict“The strongest all-around pick for hands-on planners who value privacy and depth over convenience.”
Financial Peace Personal Finance Software
Financial Peace plays a different role than its Ramsey-branded cousin: less debt-battle plan, more financial literacy curriculum wrapped in budgeting tools. Where Dave Ramsey’s Personal Finance Software 5.3 drives a specific payoff sequence, this one focuses on teaching better money habits through expense tracking and budget planning, making it a sensible pick for households starting from zero financial knowledge.
Compared with SavePoint, the ceiling is low — no simulations, no multi-currency support, no lifetime-license analytics suite. But not every buyer needs those, and the learning curve here, while present, is far gentler than SavePoint’s. Think of it as the budgeting trainer wheels: effective for what it does, outgrown once your ambitions extend past monthly budgets.
Pros:- Approachable interface suited to first-time budgeters
- Budgeting tools paired with genuine financial-literacy education
- Encourages sustainable long-term money habits
- Simpler adoption than analytics-heavy rivals like SavePoint
Cons:- Shallow feature set with no advanced planning capabilities
- Still requires some learning despite its simplicity
Best for: Financial novices and families who want an affordable habit-building tool with educational framing
Not ideal for: Growth-stage planners who need investment analysis, retirement projections, or estate documents
- Focus:Budgeting, expense tracking, financial literacy
- Skill Level:Beginner to intermediate
- Core Tools:Budgets, expense tracking, planning worksheets
- Educational Content:Included
- Advanced Features:Limited
- Learning Curve:Moderate
Our verdict“A budgeting-basics pick for learners — anyone past the beginner stage should step up to SavePoint or a retirement toolkit.”
Retirement Planning Toolkit Deluxe 2.0 [PC Download]
” image=”https://m.media-amazon.com/images/I/61RfTzIpaTL._AC_SY445_SX342_QL70_FMwebp_.jpg” link=”0″]Best for Retirement-Focused Planning
View Latest PriceWhen the question is specifically can I retire, and when, the Retirement Planning Toolkit Deluxe 2.0 is the sharpest tool in this roundup. Its 19 calculators plus worksheets and checklists dig into investment planning and financial analysis at a depth neither Financial Peace nor Dave Ramsey’s software approaches, and unlike version 1.0, this Deluxe 2.0 release adds estate-planning support and AES-256 encrypted backups.
It’s narrower than SavePoint — this is a retirement workshop, not a full personal-finance suite — and the sheer tool count can overwhelm first-timers who just want a simple budget. It’s PC-download only, with no mobile companion. But for pre-retirees who want to stress-test withdrawal rates and savings gaps on their own machine, the specialization pays off.
Pros:- 19 dedicated calculators cover withdrawal rates, savings gaps, and investment scenarios
- AES-256 encrypted backup protects sensitive financial data
- Worksheets and checklists turn analysis into an action plan
- Estate-planning support extends value beyond version 1.0
Cons:- Complex interface can overwhelm retirement-planning novices
- PC download only, with no mobile app
- Focused solely on retirement — not a full household finance solution
Best for: Pre-retirees and late-career savers who want detailed, self-guided retirement projections
Not ideal for: Beginners or general budgeters — the 19-tool interface assumes existing financial fluency
- Calculators:19
- Worksheets:Included
- Checklists:Included
- Planning Areas:Financial analysis, investment planning, estate planning
- Backup Security:AES-256 encrypted ZIP files
- Platform:PC download
- Version:Deluxe 2.0
Our verdict“The go-to choice for savers within 15 years of retirement who want rigorous, DIY retirement math on their own PC.”
Quicken Classic Deluxe for New Subscribers – 1 Year [PC/Mac Online Code]
” image=”https://m.media-amazon.com/images/I/61ypcFpjCuL._AC_SY445_SX342_QL70_FMwebp_.jpg” link=”0″]Best All-in-One Money Manager
View Latest PriceQuicken Classic Deluxe is the closest thing to a full financial command center in this lineup, which is why it earns the top spot for everyday money management. Unlike the Retirement Planning Toolkit, which focuses narrowly on retirement questions, Quicken links your banking, credit cards, debt, investments, and property accounts into one live dashboard, so your budget updates itself rather than requiring manual entry. Compared with Dave Ramsey’s Personal Finance Software, it goes well beyond budgeting into net-worth tracking and debt payoff scenarios. The tradeoff is friction: activation requires an online subscription setup, and the depth of features means newcomers face a genuine learning curve before the software pays off.
Pros:- Aggregates banking, credit, debt, investment, and property accounts in one place
- Customizable budgets and multiple debt payoff scenarios
- Works on both PC and Mac with a single subscription
- Automatic transaction sync reduces manual data entry
Cons:- Requires online activation and a recurring annual subscription
- Feature depth creates a real learning curve for first-time users
Best for: Households who want one subscription tool to track spending, budgets, debt, and investments across all linked accounts
Not ideal for: Buyers who want a one-time purchase with no subscription — SavePoint offers offline, no-subscription budgeting instead
- Platform:PC/Mac
- Duration:1 Year subscription
- Format:Online code
- Account Types Supported:Banking, credit cards, debt, investments, property
- Budgeting:Custom budgets and spending tracking
- Debt Tools:Multiple debt payoff scenarios
Our verdict“If you want a single tool that manages your whole financial life rather than one slice of it, Quicken Classic Deluxe justifies its subscription.”
Retirement Planning Toolkit Deluxe 1.0 [Download]
” image=”https://m.media-amazon.com/images/I/51kEf6q-b+L._AC_SY445_SX342_QL70_ML2_.jpg” link=”0″]Best for Retirement-Focused Planning
View Latest PriceWhere Quicken Classic Deluxe tries to manage everything, this toolkit does one thing well: answering “can I retire, and when?” Its 19 calculators, worksheets, and checklists walk through retirement age, savings, investment, and estate decisions in a structured way that general budgeting tools like Financial Peace Personal Finance Software simply don’t attempt. The AES-256 encrypted backup and restore is a thoughtful touch for sensitive financial data. Note that this is version 1.0 — the newer Retirement Planning Toolkit Deluxe 2.0 exists in this same roundup, so bargain hunters should compare prices before committing. The main tradeoff: it’s a planning aid, not a tracker, and buyers unfamiliar with financial planning terminology may find the sheer number of tools intimidating.
Pros:- 19 dedicated calculators covering retirement, investments, loans, and mortgages
- Worksheets and checklists create a step-by-step planning process
- AES-256 encrypted backup and restore protects sensitive data
- Report generation makes it easy to share outputs with a spouse or advisor
Cons:- Digital download and installation required — no browser-based access
- Can feel complex for users new to financial planning concepts
- Superseded by version 2.0, which may offer better value depending on price
Best for: Pre-retirees who want a structured, calculator-driven way to test retirement ages, savings rates, and estate decisions
Not ideal for: Anyone who wants day-to-day budgeting or live account aggregation — this is scenario planning, not money management
- Calculators Included:19
- Calculator Types:Retirement, investment, loan, mortgage
- Planning Tools:Checklists and worksheets
- Security:AES-256 encrypted backup and restore
- Reports:Report generation
- Format:Digital download
Our verdict“A focused, one-time-purchase planning companion for people within a decade of retirement who want structure more than automation.”
How We Picked
I evaluated each product through one lens: how well it helps a household plan its financial future. That meant weighing planning depth (can it project decades ahead, run scenarios, model retirement or FIRE goals?), cost structure (one-time purchase versus recurring subscription), data flexibility (offline use versus required account syncing), and learning curve. Products covering multiple planning needs ranked higher than single-purpose tools unless the single purpose was executed exceptionally well.
Ranking also reflected who each tool realistically serves. Estate planning and retirement-only tools couldn’t compete as all-around picks, so they earned category-specific placements instead. Where two products overlapped directly — the Ramsey titles and the two Retirement Planning Toolkit versions — I ranked the newer or more capable version higher and flagged the alternative as a value option.
Factors to Consider When Choosing Financial Planning Software
Before picking a financial planning tool, it helps to understand the broader landscape and the mistakes buyers commonly make with this category of software.Subscription vs. One-Time Purchase
The biggest cost mistake buyers make is comparing sticker prices instead of five-year costs. A $50 one-time tool beats a $35-per-year subscription after roughly 18 months, and most planning software stays usable for far longer than that. Subscriptions justify themselves when they include live services — automatic bank downloads, transaction categorization, and synced account balances. If a subscription product only offers the same static calculations an offline tool provides, you’re paying rent on a spreadsheet. Buyers should also check whether offline tools charge for major version upgrades, since a ‘free forever’ promise sometimes hides paid point releases.
Planning Depth: Budgeting Is Not Financial Planning
Many shoppers conflate budgeting tools with planning tools, then feel disappointed when the software can’t answer questions like ‘can I retire at 55?’ A budget tracks what already happened; a plan projects what could happen. Tools with Monte Carlo simulations, balance sheet tracking, and multi-decade cash flow projections sit in the planning camp. If your real goal is retirement readiness or financial independence, prioritize projection capability over pretty spending charts. Conversely, if you simply overspend monthly, a sophisticated simulator adds complexity without solving your problem.
Offline Tools and Data Portability
Offline-first software has real advantages: no account linking means no credentials stored with a vendor, and no cloud dependency means your plan still works when a company shuts down a server. The tradeoff is manual data entry, which is the number one reason people abandon financial software within three months. Before buying, honestly assess whether you’ll maintain monthly updates by hand. Also check export formats — a planner that traps your history in a proprietary file creates painful migration later. CSV export should be considered a minimum requirement for any long-term planning tool.
Estate Documents Deserve Their Own Purchase
Buyers often assume one program can handle wills, trusts, budgets, and retirement projections. In practice, estate document software and financial planning software are different disciplines with different legal requirements. Will and trust tools must stay current with state law, which is why they release annual editions — using a three-year-old version risks invalid documents. A common mistake is treating an estate tool as a bonus feature rather than checking whether it covers your specific state’s requirements. Budget for it as a separate purchase, and expect to update it every few years.
Estate of Retirement-Only Tools: Matching Scope to Your Question
Retirement-focused toolkits are tempting because they answer one big question directly, but scope matters. A dedicated retirement toolkit typically models withdrawals, Social Security timing, and portfolio longevity better than a general budget app — yet it won’t help you fix the savings shortfall it reveals. General-purpose planners show the whole picture but may simplify retirement-specific assumptions like sequence-of-returns risk. If retirement is 20 years away, a broad planner builds better habits; if it’s 5 years away, a dedicated retirement model gives sharper answers. Some households genuinely benefit from owning both types.
Version Timing and Upgrade Traps
Several titles in this category ship numbered versions, and buying the wrong edition is an easy mistake. Older versions get discounted once successors launch, but the savings can be false economy if the newer release fixed calculation bugs or updated tax assumptions. Check what specifically changed between versions before choosing the cheaper one — changelogs usually reveal whether the update is cosmetic or substantive. Also watch for PC-download versus physical-media differences, since a USB edition can be reinstalled on a new computer while some download licenses are single-machine. Tax-law-dependent features age fastest, so recency matters most for anything touching retirement accounts or estate rules.
Frequently Asked Questions
Is offline financial planning software as good as cloud-based options?
For projection and planning work, offline tools are often better because they never hold your banking credentials and keep functioning regardless of vendor decisions. SavePoint demonstrates this well, running Monte Carlo simulations and balance sheets entirely without an internet connection. The real cost is convenience: you’ll manually enter account balances instead of getting automatic syncs. Cloud tools like Quicken Classic Deluxe win on freshness of data, which matters for daily budgeting but matters far less for long-range planning where quarterly updates suffice. Many serious planners actually prefer manual entry because it forces them to look at their numbers regularly.
Do I need Quicken WillMaker if I already have financial planning software?
Yes, if you don’t yet have a will, trust, power of attorney, or healthcare directive — planning software and estate documents solve unrelated problems. No budgeting or retirement tool in this category generates legally valid estate documents. WillMaker’s value is that it produces state-specific documents at a fraction of an attorney’s fee, which is appropriate for straightforward estates. If you have significant assets, blended families, or complex wishes, software-generated documents should be reviewed by a lawyer rather than relied on blindly. Plan to repurchase or update the software every few years since estate law changes.
Is the Retirement Planning Toolkit 2.0 worth the extra cost over version 1.0?
For most buyers, yes. The 2.0 release is the version actively maintained, and retirement math is exactly the kind of calculation where you don’t want to inherit bugs from a prior edition. Version 1.0 becomes attractive only when discounted heavily and when your needs are basic projections rather than detailed scenario testing. Before choosing, confirm whether files from 1.0 import into 2.0, since re-entering decades of assumptions is tedious. A reasonable rule: if the price gap is under about 30%, take the newer version and skip the risk. If you’re buying for a one-time question, the older edition can be a legitimate budget play.
Which of these tools actually helps me retire early (FIRE)?
SavePoint is the only one in this lineup with explicit FIRE planning built in, including the Monte Carlo simulations that early-retirement math depends on. FIRE planning stresses a tool differently than ordinary retirement planning because the withdrawal period can stretch 40-plus years, making sequence-of-returns risk far more dangerous. Generic budget tools fail here because they optimize for monthly outcomes, not decades-long portfolio survival. Quicken Classic Deluxe can track the savings rate that fuels FIRE but won’t tell you whether your plan survives a bad market early on. If FIRE is your goal, simulation capability should be your first filter, not a nice-to-have.
Why do Dave Ramsey’s two software titles exist separately, and which should I buy?
They target overlapping but distinct audiences within the Ramsey ecosystem. The Personal Finance Software version 5.3 is the more general envelope-style budgeting tool following the baby-steps methodology, while Financial Peace pairs planning with the educational program structure. If you already own Financial Peace materials through a class or membership, check whether software access is included before buying either. If you’re self-directed and just want the budgeting mechanics, the standalone software is the simpler purchase. Neither is the strongest pure planner in this lineup — their appeal is the Ramsey method itself, so buy them for the philosophy, not the analytics.
Conclusion
The right pick depends entirely on what you’re planning for. SavePoint is my best overall choice because it covers budgeting, balance sheets, FIRE projections, and Monte Carlo simulations without a subscription — the broadest planning capability per dollar here. Best value goes to the Retirement Planning Toolkit 1.0, which delivers focused retirement modeling at a clearance-style price if you can live without the 2.0 refinements. Quicken Classic Deluxe is the premium pick, justified only if automatic bank downloads and polished transaction management are worth an annual fee. Beginners should start with Ramsey’s Personal Finance Software 5.3, since envelope budgeting teaches fundamentals before you tackle simulations. For specific needs: Quicken WillMaker & Trust 2026 for estate documents, Retirement Planning Toolkit Deluxe 2.0 for near-term retirement questions, and Financial Peace if you want software bundled with structured financial education. Match the tool to your single biggest unanswered question, and you won’t overspend on capability you’ll never open.
NFL season / tailgating Picks
team gear
As an affiliate, we earn on qualifying purchases.