Debt payoff planners help you list balances, track payments, and keep a repayment plan visible without relying on a spreadsheet. My best overall pick is The Debt Payoff Planner: A 12-Week Guided Sprint, which pairs snowball and avalanche trackers with budget worksheets and sinking funds. For a simpler, more flexible record-keeping approach, the 8.5″ x 11″ Financial Tracker Notebook offers a larger writing format, while the Snowball Debt Payoff Planner suits readers who want to focus on one familiar payoff method. The main tradeoffs are guided structure versus open-ended logging, larger pages versus easier portability, and a focused debt tracker versus a broader money planner. Read on for the full comparison and guidance on choosing a planner that you will keep using.

Get smart everyday buys delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
Key Takeaways
- The 12-Week Guided Sprint stands apart because it combines snowball and avalanche tracking with budget worksheets and sinking-fund planning, rather than only logging debts.
- The two 8.5-by-11-inch options prioritize writing room; their larger format may suit detailed entries better than the 6-by-9-inch logbooks, which are easier to carry.
- Snowball-focused titles are method-specific, while general debt trackers leave more room for readers who prefer the avalanche method or want to choose later.
- Many titles promise similar basic tracking, so buyers should compare page size, stated page count, and guidance instead of relying on the words “simple” or “planner.”
- The guide-style title and short sprint format serve different needs: one signals explanatory material, while the other offers a defined planning period and practical worksheets.




| debt payoff planner | Format | Size | Product type |
|---|---|---|---|
| Debt Payoff Planner | — | — | Debt payoff planner and budget notebook |
| Debt Payoff Planner: Simple De | — | 6 x 9 inches | Debt tracking log book |
| Debt Snowball Tracker: Debt Re | Notebook | — | Debt reduction strategy planner |
| Debt Repayment Planner: Log Bo | Physical log book | 6 x 9 inches | Debt repayment planner and log book |
| Snowball Debt Payoff Planner | — | — | Debt payoff planner |
| Debt Payoff Planner: Simple De | Printed planner | 8.5 x 11 inches | — |
| Debt Payoff Planner: Simple De | Planner | — | — |
| Debt Payoff Planner: Simple De | Planner | 8.5 x 11 inches | — |
| Debt Payoff Planner: A Simple | Planner | 6 x 9 inches | — |
| Debt Payoff Planner: Simple De | Planner | Not specified | — |
| Debt Payoff Planner & Payment | Notebook | 6 x 9 inches | Debt payoff planner and payment logbook |
| Debt Payoff Planner | Notebook | — | — |
| Debt Payoff Planner: Simple De | Not specified | Not specified | Debt payoff planner and payment tracker |
| Debt Payoff Planner: A Guide t | — | 8.5 x 11 inches | Debt payoff planner and financial guide |
| The Debt Payoff Planner: A 12- | — | — | — |
More Details on Our Top Picks
Debt Payoff Planner – Budget Notebook with Flower Cover Design
For someone who wants a straightforward place to record debts and watch balances move, this planner keeps the focus on basic payoff tracking rather than a detailed financial system. Its description includes student loans as well as other debt, making it a flexible pick for borrowers with more than one type of balance. Compared with the Debt Snowball Tracker: Debt Reduction Strategy Planner, this notebook is not specifically framed around the snowball method, so it may suit people who prefer to choose their own repayment order. The tradeoff is limited product detail: the page count, size, and specific worksheet formats are not provided. The flower cover adds personality, but buyers who need clear instructions or a defined planning structure may prefer the Snowball Debt Payoff Planner, which lists a three-year plan.
Pros:- Simple layout is suited to recording debt information and progress
- Description includes student loans as well as debt repayment more broadly
- Does not tie the buyer to a particular payoff strategy
- Flower cover design gives the notebook a more personal look
Cons:- Page count, size, and format are not specified
- No detailed financial planning tools or payoff instructions are described
- Limited feature information makes it difficult to judge how much tracking space it provides
Best for: Borrowers who want a simple paper log for monitoring student loans and other debts without committing to a named payoff method
Not ideal for: Planners who need a specified page count, known dimensions, detailed strategy instructions, or a clearly described set of worksheets
- Product type:Debt payoff planner and budget notebook
- Cover design:Flower design
- Layout:Simple layout
- Purpose:Track financial situation and debt repayment progress
- Debt types mentioned:Student loans and other debts
- Payoff strategy:No specific strategy stated
Our verdict“Choose this for a flexible, uncomplicated debt log, but pick a planner with stated dimensions and worksheets if structure matters to you.”
Debt Payoff Planner: Simple Debt Tracking Log Book to Organize Payments & Improve Financial Control
This is the clearest fit for buyers who want a portable, dedicated debt record: it specifies 108 pages in a 6 x 9-inch format. That defined footprint makes it easier to compare with the Debt Repayment Planner: Log Book Tracker for Credit and Loan Payoff, which is also 6 x 9 inches but has 100 pages and mentions personal budgeting. This planner instead puts its emphasis on logging and planning debt reduction. Its narrow scope can be an advantage if you want debt details kept separate from broader household budgeting, but it also means it is not a full money-management workbook. There are no digital features or integrations described, and the basic design may feel plain to buyers who want more visual guidance. I would choose it for straightforward, portable record-keeping, not for strategy coaching.
Pros:- Specified 108-page length gives buyers a clearer sense of available space
- 6 x 9-inch size is compact for carrying or storing
- Dedicated focus on debt payment logging and reduction planning
- Simple design can keep routine tracking uncomplicated
Cons:- Limited to debt tracking, without additional financial tools described
- No digital features or integrations are specified
- Basic design may not appeal to buyers who want more visual prompts or guidance
Best for: People who want a compact, page-count-defined notebook for recording debt payments and payoff plans on the go
Not ideal for: Buyers seeking budgeting worksheets, payoff-method instructions, digital tracking, or a planner that combines multiple areas of personal finance
- Product type:Debt tracking log book
- Page count:108 pages
- Size:6 x 9 inches
- Primary use:Organizing and tracking debt payments
- Planning focus:Debt reduction strategies
- Digital features:None specified
Our verdict“Choose this compact 108-page log if portability and defined dimensions matter more than broader budgeting tools or digital tracking.”
Debt Snowball Tracker: Debt Reduction Strategy Planner
When the hardest part of debt repayment is staying engaged, this tracker’s distinct strength is its snowball-method focus: it is designed to help users follow progress and maintain motivation with a simple, do-it-yourself format. That makes it a more method-specific choice than the Flower Cover Design planner, which describes general debt tracking without naming a repayment approach. The difference matters if you have decided to prioritize smaller balances first and want a notebook centered on that process. The tradeoff is that the listing does not describe detailed financial worksheets or explain how to use the strategy. Compared with the Snowball Debt Payoff Planner, which specifies a three-year plan, this tracker offers less clearly stated structure. It suits buyers who already understand their method and mainly want a visual record of progress.
Pros:- Explicitly designed around the debt snowball method
- Progress tracking can help make payoff milestones visible
- Simple DIY approach avoids an overly complex planning system
- Focused strategy gives it a clearer purpose than a general debt log
Cons:- Detailed financial planning features are not described
- No included instructions for debt strategies are specified
- Page count and physical dimensions are not provided
Best for: Borrowers committed to the debt snowball approach who want a simple paper tracker to maintain momentum
Not ideal for: People who need payoff-method instructions, a broad budget system, or a stated page count and size before buying
- Product type:Debt reduction strategy planner
- Named method:Debt snowball
- Format:Notebook
- Approach:Simple, do-it-yourself tracking
- Primary purpose:Track debt payoff progress
- Page count:Not specified
Our verdict“Pick this if you already plan to use the snowball method and want a simple motivation-focused tracker rather than a guided financial workbook.”
Debt Repayment Planner: Log Book Tracker for Credit and Loan Payoff, Personal Budgeting (6×9 Inches, 100 Pages)
This planner stands out for bringing credit and loan payoff tracking together with personal budgeting in a defined 6 x 9-inch, 100-page log book. That gives it a broader role than the 108-page Debt Payoff Planner: Simple Debt Tracking Log Book, whose description stays focused on debt reduction. The tradeoff is that this is still a physical record-keeping tool, not a digital system with backup or integrations. Its listed format helps buyers judge portability and space, but the description does not spell out particular budgeting worksheets or repayment guidance. I would favor it over the narrower log if you want to keep basic budget notes alongside debts; if your priority is a named strategy, the Debt Snowball Tracker offers a more specific method focus.
Pros:- Covers credit and loan payoff tracking
- Personal budgeting is included in the planner’s stated purpose
- 6 x 9-inch size offers a defined, compact format
- 100-page count gives buyers a clear indication of notebook length
Cons:- Physical logging only, with no digital backup described
- No digital integrations are specified
- Specific budgeting worksheets and payoff guidance are not detailed
Best for: People who want one compact notebook for logging credit and loan repayment alongside basic personal budget records
Not ideal for: Users who need digital backup, automated tracking, detailed payoff instructions, or a planner centered on one named debt strategy
- Product type:Debt repayment planner and log book
- Size:6 x 9 inches
- Page count:100 pages
- Debt types:Credit and loans
- Additional focus:Personal budgeting
- Format:Physical log book
Our verdict“Choose this if you want a compact paper record that pairs debt tracking with basic budgeting, and skip it if you need digital tools.”
Snowball Debt Payoff Planner
The standout here is a stated three-year plan paired with simple debt trackers, giving buyers a longer planning horizon than the Debt Snowball Tracker, whose listing emphasizes motivation and progress but does not specify a timeline. It is aimed at organizing debts, loans, and credit cards, so it can serve borrowers tracking several kinds of balances within a snowball-style payoff effort. The green, brown, and gold cover adds a distinctive look, while the core remains a paper tracker rather than a digital finance tool. Its main limitation is the lack of detailed instructions: a three-year outline is useful only if you are comfortable deciding how to apply it. Compared with the Debt Repayment Planner, it offers a named plan but does not describe a personal budgeting focus.
Pros:- Includes a stated three-year payoff plan
- Simple debt trackers support progress monitoring
- Description covers debts, loans, and credit cards
- Distinctive green, brown, and gold cover design
Cons:- Detailed payoff instructions or strategy guidance are not described
- No digital or online features are specified
- Focused on debt tracking rather than broader budgeting tools
Best for: Borrowers using a snowball-style approach who want a multi-year framework for tracking loans, credit cards, and other debts
Not ideal for: People who need step-by-step strategy guidance, digital tracking, or budgeting worksheets alongside debt payoff records
- Product type:Debt payoff planner
- Plan duration:3 years
- Tracking tools:Simple debt trackers
- Debts mentioned:Debts, loans, and credit cards
- Cover colors:Green, brown, and gold
- Digital features:None specified
Our verdict“Choose this for a snowball-oriented, three-year tracking framework, but look elsewhere if you need detailed coaching or digital tools.”
Debt Payoff Planner: Simple Debt Payment Tracker to Pay off Credit Card Debt and Organize Finances
For someone whose main goal is getting credit card balances organized, this planner keeps its scope clear: payment tracking and debt organization, without suggesting it includes a full budget system. Its 105 pages and 8.5 x 11-inch format offer room to write, making it a better fit for desk-based planning than the more compact 6 x 9-inch Debt Payoff Planner: A Simple Debt Tracker to Manage and Organize Your Debt. That larger page size can make entries easier to read, but it is less convenient to carry. The tradeoff is a narrow toolkit: the supplied details do not indicate budget worksheets, payoff-strategy guidance, or digital tools. I would choose it over a general-purpose tracker only when credit card payment organization is the priority.
Pros:- Focused on organizing and tracking debt payments
- Large 8.5 x 11-inch pages provide generous writing space
- 105 pages support ongoing paper-based tracking
Cons:- No additional financial tools or features are specified
- Limited to debt tracking rather than broader budgeting
- Large format is less portable than a 6 x 9-inch option
Best for: People managing credit card balances who want a roomy paper planner focused on recording debt payments.
Not ideal for: Buyers who want budgeting worksheets, payoff-method instruction, digital syncing, or a compact planner to carry around.
- Pages:105
- Size:8.5 x 11 inches
- Format:Printed planner
- Primary focus:Debt payment tracking
- Debt type mentioned:Credit card debt
- Organization focus:Financial situation and debt payments
Our verdict“Choose this planner if credit card tracking and roomy pages matter more to you than budgeting tools or portability.”
Debt Payoff Planner: Simple Debt Tracker for Managing Credit Card and Debt Payments
This is the most straightforward choice in the group for buyers who want to keep several debts visible in one paper tracker. The description highlights credit cards and multiple debts, with a simple system intended to help users monitor progress and stay organized. Unlike Debt Payoff Planner: Simple Debt Payment Tracker to Pay off Credit Card Debt and Organize Finances, this listing does not provide page count or dimensions, so I cannot judge its writing capacity or portability from the supplied information. Its simplicity may suit someone who already knows how they plan to repay balances, but the planner is not described as offering financial analysis, budgeting tools, or app integration. I would favor a more detailed guided planner for users who need help choosing a repayment strategy; this one is better suited to recording progress.
Pros:- Designed to track multiple debts, including credit cards
- Simple structure may be easy to maintain regularly
- Progress monitoring can help keep repayment goals visible
Cons:- No detailed financial analysis features are described
- No digital or app integration is specified
- Page count and physical dimensions are not provided
Best for: People tracking several credit cards or other debts who want a simple paper-based way to monitor payments and progress.
Not ideal for: Buyers who need detailed financial analysis, budgeting support, digital access, or confirmed page and size information before choosing.
- Format:Planner
- Primary focus:Debt tracking and payment management
- Debt types mentioned:Credit card and other debts
- Tracking emphasis:Progress monitoring
- Organization emphasis:Managing multiple debts
- Digital integration:Not specified
Our verdict“Pick this option if you want a basic tracker for multiple balances and do not need financial analysis or digital tools.”
Debt Payoff Planner: Simple Debt Payoff Tracker to Organize your Financial Situation – 8.5″ x 11″ 100+ Pages
The title gives buyers two useful details up front: a large 8.5 x 11-inch page size and more than 100 pages. That makes this a plausible fit for people who prefer substantial writing space and want a dedicated paper tracker for organizing debt. Compared with Debt Payoff Planner: Simple Debt Payment Tracker to Pay off Credit Card Debt and Organize Finances, it advertises a similar large format and page capacity, so the available information does not show a clear functional advantage over that credit-card-focused option. The description field supplies no further details, which leaves the actual layout, included tracking sections, and any budgeting or payoff guidance unconfirmed. I would shortlist it for its stated size, but choose a planner with clearer feature information if the page layout matters to your repayment routine.
Pros:- Stated 8.5 x 11-inch format offers a broad writing area
- Advertised as having more than 100 pages
- Dedicated to debt payoff tracking and financial organization
Cons:- The supplied information does not describe specific planner sections
- Exact page count is not provided
- No budgeting, payoff-strategy, or digital features are confirmed
Best for: Paper-planner users who want a large writing area and more than 100 pages for organizing debt information.
Not ideal for: Buyers who need confirmed worksheets, a specified exact page count, payoff-method guidance, or a compact book.
- Format:Planner
- Size:8.5 x 11 inches
- Pages:100+
- Primary focus:Debt payoff tracking
- Organization focus:Financial situation
- Specific worksheets:Not specified
Our verdict“Choose this if large pages and a 100-plus-page format are your main requirements, but look elsewhere for clearly documented planning tools.”
Debt Payoff Planner: A Simple Debt Tracker to Manage and Organize Your Debt
The listed 1,085 pages make this the standout choice for buyers who want an unusually large amount of space for debt records. Its 6 x 9-inch format is more portable than the 8.5 x 11-inch Debt Payoff Planner: Simple Debt Payment Tracker to Pay off Credit Card Debt and Organize Finances, though it also means less room per page. The sheer page count could appeal to someone planning to keep a long-running record, but it does not imply a richer toolkit: the supplied description mentions organization and debt management, not budgeting worksheets, calculators, or payoff-method guidance. I would verify that the unusually high page count matches the physical book you want. This is a specialized pick for abundant tracking space, not for people seeking a guided financial system.
Pros:- Listed 1,085 pages provide extensive capacity for records
- 6 x 9-inch size is more compact than large-format planners
- Designed to organize and manage debt
Cons:- The listed page count is unusually high and may warrant verification
- Smaller pages offer less writing room than 8.5 x 11-inch planners
- No additional financial tools are described
Best for: People who want a compact-format debt log with extensive listed page capacity for maintaining long-term records.
Not ideal for: Buyers who prioritize a light, easy-to-carry notebook, broad writing space per page, or built-in budgeting and payoff guidance.
- Pages:1,085
- Size:6 x 9 inches
- Format:Planner
- Primary focus:Debt tracking
- Organization focus:Managing and organizing debt
- Additional tools:Not specified
Our verdict“Consider this for a long-term debt log with a compact footprint, but not if you need guided repayment or broad worksheets.”
Debt Payoff Planner: Simple Debt Payoff Tracker
With 110 pages described as supporting systematic debt tracking, this planner suits buyers who want to make debt repayment a recurring paper-planning task. Its stated emphasis on organizing financial goals gives it a slightly broader framing than Debt Payoff Planner: A Simple Debt Tracker for Managing Credit Card and Debt Payments, which is presented mainly as a basic tracker for multiple balances. Still, neither description confirms budgeting worksheets or digital tools, and this planner remains focused on debt rather than overall cash flow. The product data also omits dimensions, so I cannot compare its portability or writing space with the 8.5 x 11-inch options. I would pick it when its stated page count and goal-oriented approach fit your routine, but not when specific layouts or broader financial planning features are decisive.
Pros:- 110 pages are specified for ongoing planning
- Supports organizing financial goals alongside debt tracking
- Simple tracking approach may suit a repeatable repayment routine
Cons:- No budgeting tools are described
- Physical dimensions are not provided
- Limited to debt tracking rather than a broader financial plan
Best for: People who want a paper-based debt tracker with a stated 110 pages and a focus on organizing repayment goals.
Not ideal for: Buyers who need budgeting tools, a confirmed book size, digital tracking, or a guided snowball or avalanche plan.
- Pages:110
- Format:Planner
- Primary focus:Debt payoff tracking
- Planning emphasis:Organizing financial goals
- Repayment approach:Systematic debt repayment
- Size:Not specified
Our verdict“Choose this for a straightforward 110-page paper tracker tied to repayment goals, and skip it if you need broader planning features.”
Debt Payoff Planner & Payment Logbook: Manage and Organize Your Debt to Take Control of Your Financial Situation, Money Tracker Notebook, 6 x 9 inch
This 6 x 9-inch logbook is the clearest fit here for someone who wants to track payments using the debt snowball method without a broad financial-planning workbook. Its compact format may be easier to keep with everyday notes than the large Debt Payoff Planner – 8.5″x11″ Financial Tracker Notebook, which is better suited to people who want more room for balances, dates, and strategy entries. The tradeoff is that this logbook is described as a focused tracker, not a place for detailed budgeting or extensive notes. I’d choose it for a straightforward repayment routine and skip it if you need worksheets for several parts of your finances. Among these options, its specific snowball emphasis gives it a more defined purpose than the basic tracker in the Simple Debt Payment Tracker and Organizer listing.
Pros:- Supports the debt snowball repayment method
- Designed to organize and track debt payments
- Simple format suits users who prefer a focused logging routine
- 6 x 9-inch size is more compact than the 8.5 x 11-inch tracker in this roundup
Cons:- Does not provide detailed financial-planning features
- Limited space may not suit extensive notes or complex repayment plans
Best for: People with a short list of debts who want a compact, straightforward logbook built around the snowball repayment method.
Not ideal for: Buyers who need detailed budget planning, extensive writing space, or worksheets for financial goals beyond debt payments.
- Product type:Debt payoff planner and payment logbook
- Size:6 x 9 inches
- Repayment method:Debt snowball
- Primary use:Organizing and tracking debt payments
- Format:Notebook
- Detailed financial planning:Not specified as included
Our verdict“Choose this compact logbook if you want a simple snowball-based payment tracker rather than a broader financial workbook.”
Debt Payoff Planner – 8.5″x11″ Financial Tracker Notebook, 53 Sheets
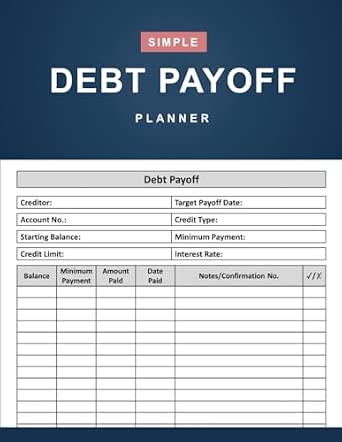
This is the most clearly specified choice for buyers who want to record the moving parts of repayment, including balances, due dates, and interest rates, then use structured pages to plan their strategy. Its 8.5 x 11-inch spiral-bound format offers more writing space than the 6 x 9-inch Debt Payoff Planner & Payment Logbook, making it a better fit for people tracking several accounts or adding detailed entries. That larger page size comes with a practical compromise: it is less compact to carry, and the listing describes 53 sheets, so it may not cover a long-running plan without replacement. Compared with The Debt Payoff Planner’s 12-week guided sprint, this notebook puts more emphasis on tracking account details than on a time-boxed program.
Pros:- Structured pages cover balances, due dates, and interest rates
- Large 8.5 x 11-inch pages allow room for detailed entries
- Includes pages for repayment strategies and financial goals
- Spiral binding allows the notebook to open flat for writing
Cons:- The listed 53 sheets may require replacement during long-term use
- Large format is less portable than the 6 x 9-inch logbook
- Spiral binding may be less durable over time, according to the product information
Best for: People managing multiple debts who want generous page space to record balances, due dates, interest rates, and repayment goals.
Not ideal for: Buyers seeking a compact planner, a long-term supply of pages, or a guided program that includes budgeting tools beyond debt tracking.
- Format:Notebook
- Paper size:8.5 x 11 inches
- Binding:Spiral-bound
- Pages:115 pages
- Sheets:53 sheets
- Calendar type:Monthly
- Item weight:0.26 kg
- Cover material:Polycarbonate (PC)
- Materials:Paper
Our verdict“Pick this notebook if detailed account tracking and writing space matter more than portability or a guided multiweek program.”
Debt Payoff Planner: Simple Debt Payment Tracker and Organizer to Control Your Financial Situation and Pay Off Credit Card Debt
This listing is best read as a basic debt-payment organizer for someone who wants a systematic way to track credit-card payoff without needing a named repayment method or a broad set of worksheets. The supplied details emphasize ease of use, but do not identify its size, page count, binding, or specific tracking tools. That makes it harder to judge how much room it gives you compared with the clearly specified Debt Payoff Planner – 8.5″x11″ Financial Tracker Notebook, which lists fields for balances, due dates, and interest rates. It is also less prescriptive than The Debt Payoff Planner’s 12-week guided sprint, whose snowball and avalanche trackers provide a more defined process. I’d consider this only if a simple organizer is your priority and you can confirm the physical format before buying.
Pros:- Designed to organize and track debt payments
- Aims to support systematic credit-card debt payoff
- User-friendly design is suited to straightforward tracking
Cons:- The available description does not specify detailed tracking tools
- Size, page count, and binding are not provided
- No digital components or additional physical materials are specified
Best for: Credit-card borrowers who want a simple, user-friendly way to organize payments and do not need a specific repayment framework.
Not ideal for: Buyers who need confirmed page dimensions, detailed account fields, budgeting worksheets, or a guided payoff schedule.
- Product type:Debt payoff planner and payment tracker
- Primary use:Organizing debt payments
- Debt focus:Credit-card debt
- Format:Not specified
- Size:Not specified
- Page count:Not specified
Our verdict“Consider this for uncomplicated credit-card payment tracking only if the product format meets your needs.”
Debt Payoff Planner: A Guide to Eliminating Debt and Managing Finances
The combination of a stated financial-management guide, debt payment tracker, and 140 pages makes this the most guide-oriented option among the simple trackers in this group. Its 8.5 x 11-inch layout also offers more writing room than the 6 x 9-inch Debt Payoff Planner & Payment Logbook, which is better suited to compact snowball logging. The larger format may help readers who want space to work through debt and credit-card organization, but the product details do not explain what the guide teaches or how its tracker is structured. That lack of detail makes it harder to compare its method with the specific balance, due-date, and interest-rate fields listed for the 8.5 x 11-inch Financial Tracker Notebook. I’d choose it for its guide-and-tracker emphasis, while treating the unspecified content as a real limitation.
Pros:- Includes a debt payment tracker
- Described as a guide to debt elimination and financial management
- 140 pages provide a substantial amount of space
- 8.5 x 11-inch layout offers more writing room than compact options
Cons:- The available description does not detail the guide’s contents
- Specific tracker fields and repayment strategies are not identified
- Large format is less portable than a 6 x 9-inch logbook
Best for: Readers who want a large-format debt planner that pairs a payment tracker with guidance on managing finances and credit cards.
Not ideal for: Buyers who need a clearly described repayment method, specific worksheet details, or a compact notebook to carry around.
- Product type:Debt payoff planner and financial guide
- Size:8.5 x 11 inches
- Pages:140
- Tracker:Debt payment tracker
- Topics:Debt elimination, credit cards, and financial management
- Binding:Not specified
Our verdict“Choose this if you want a large guide-and-tracker format, but not if you need detailed information about its worksheets before deciding.”
The Debt Payoff Planner: A 12-Week Guided Sprint to Financial Freedom with Snowball & Avalanche Trackers, Budget Worksheets & Sinking Funds
This planner has the strongest stated process in the group: a 12-week guided sprint paired with both snowball and avalanche trackers, budget worksheets, and sinking-fund planning. That combination makes it more action-oriented than the Debt Payoff Planner – 8.5″x11″ Financial Tracker Notebook, which lists useful account fields but focuses on ongoing debt tracking rather than a defined program. It also reaches beyond the payment-log approach of the 6 x 9-inch Debt Payoff Planner & Payment Logbook by including budgeting and savings tools. The tradeoff is that the available product data gives no size, page count, binding, or material details, so its physical format and writing space are unknown. I’d favor it for someone who wants a structured short-term framework, not someone choosing primarily by notebook specifications.
Pros:- Provides a structured 12-week payoff program
- Includes both snowball and avalanche trackers
- Budget worksheets connect repayment planning with spending decisions
- Sinking-fund tools extend planning beyond debt payments
Cons:- Physical format, size, and binding are not specified
- Page count and available writing space are not provided
- A 12-week structure may not suit buyers seeking an open-ended tracker
Best for: People who want a time-boxed repayment program with both snowball and avalanche methods, plus budgeting and sinking-fund worksheets.
Not ideal for: Buyers who need confirmed page dimensions, a known page count, or an open-ended payment log without a 12-week program structure.
- Program length:12 weeks
- Repayment methods:Snowball and avalanche
- Debt tools:Debt trackers
- Budgeting tools:Budget worksheets
- Savings tools:Sinking-fund planning
- Physical format:Not specified
Our verdict“Choose this for a guided, short-term payoff framework that combines repayment methods with budgeting and sinking-fund planning.”
How We Picked
I compared the 15 planners by how directly their stated format and focus support a real debt payoff routine: listing accounts, recording balances and payments, and keeping a chosen strategy visible. I gave more weight to products whose titles identify useful distinctions—such as a guided 12-week sprint, snowball-specific tracking, larger pages, or a stated page count—than to listings that make broadly similar promises of simple debt organization.
The ranking favors tools that appear to offer a clearer path from planning to ongoing use, while still accounting for flexibility and ease of carrying. The guided sprint leads because its described worksheets and two payoff methods offer a wider planning toolkit; simpler logbooks rank as practical choices for readers who want less structure. Since the supplied product details do not establish paper quality, binding, or exact interior layouts for most listings, I do not treat those qualities as proven advantages.
| debt payoff planner | Format |
|---|---|
| Debt Payoff Planner | — |
| Debt Payoff Planner: Simple De | — |
| Debt Snowball Tracker: Debt Re | Notebook |
| Debt Repayment Planner: Log Bo | Physical log book |
| Snowball Debt Payoff Planner | — |
| Debt Payoff Planner: Simple De | Printed planner |
| Debt Payoff Planner: Simple De | Planner |
| Debt Payoff Planner: Simple De | Planner |
| Debt Payoff Planner: A Simple | Planner |
| Debt Payoff Planner: Simple De | Planner |
| Debt Payoff Planner & Payment | Notebook |
| Debt Payoff Planner | Notebook |
| Debt Payoff Planner: Simple De | Not specified |
| Debt Payoff Planner: A Guide t | — |
| The Debt Payoff Planner: A 12- | — |
Factors to Consider When Choosing Debt Payoff Planners
Before choosing a debt payoff planner, decide what job you need it to do. A notebook can help you organize information and stay accountable, but it cannot choose a safe payment amount or replace accurate lender records. These broader checks can help you select a format and planning style you can maintain.
Choose a payoff method you can maintain
The snowball method directs extra payments toward the smallest balance, while the avalanche method targets the debt with the highest interest rate. A method-specific planner can make it easier to stick with one path, but it may feel restrictive if your priorities change. A flexible tracker lets you choose or switch methods, though you may need to create your own rules and checkpoints. Before buying, decide whether seeing quick account closures or reducing interest costs is the stronger motivator for you. Keep making required minimum payments on every account, and check your lender terms before changing payment arrangements.
Match page size to how you will use it
A larger notebook can make room for handwritten notes, multiple accounts, and monthly reviews, but it is less convenient to carry or store. A compact logbook may fit a bag or desk drawer more easily, yet smaller pages can feel crowded if you track many debts or add detailed notes. Think about where you will update it: at home beside bills, during a weekly money check-in, or while away from your usual workspace. A planner that stays accessible is more useful than one with generous space that you rarely open. If the listing gives dimensions, compare them with a notebook you already like using.
Look beyond the word “simple”
Product titles often describe a planner as simple, but that does not reveal how its pages are arranged or how much guidance it provides. Some buyers need a place to record balances and due dates; others benefit from prompts, budget worksheets, or a defined review schedule. A sparse log can be easier to personalize, while a guided format can reduce the effort of deciding what to track next. Avoid assuming that a title’s broad claims guarantee a particular worksheet or layout. Check the available interior details and choose the least complicated format that still supports your routine.
Check capacity against the number of accounts
Count the debts you plan to track, including cards, personal loans, and other balances, then think about how often you want to record updates. A notebook with a stated page count offers one useful clue, but it does not tell you how those pages are divided among accounts, monthly logs, or notes. If you have several debts, look for clear interior previews or descriptions before assuming every account will have enough space. Buyers with only one or two balances may find a compact log more manageable than a large workbook. Leave room for new balances or changing payment details if your financial picture is likely to shift.
Keep the planner separate from official account records
A handwritten planner is a personal tracking aid, not the definitive record of a lender’s balance, interest, or payment posting date. Update it from statements or account portals and reconcile entries regularly, especially when interest or fees change the amount owed. A missed update can make a payoff timeline misleading, even if the planner itself is well organized. Avoid writing full account numbers or sensitive login information in a notebook that could be lost. If you want automatic balance updates or reminders, a paper planner may need to work alongside a secure digital tool.
Pay for guidance only when you will use it
Extra structure can help when you are starting from scratch or want a set schedule for reviewing spending and repayments. But worksheets and prompts add little if you already have a dependable routine and only need a place to log payments. A focused sprint can create momentum over a defined period, while a more open-ended notebook may suit debt repayment that extends beyond a short planning cycle. Decide whether guided exercises answer a real gap in your habits before choosing a more involved format. The best fit is the planner whose extra features support actions you will repeat, not simply the one with the most sections.
Frequently Asked Questions
Should I choose a snowball planner or a planner that tracks both snowball and avalanche methods?
Choose a snowball-focused planner if paying off smaller balances first helps you stay motivated and you are comfortable following that method. A planner that supports both methods gives you more room to compare approaches or revise your plan as your circumstances change. The avalanche method may reduce interest costs when you direct extra payments to the highest-rate balance, but progress can feel slower at first. Neither planner can decide what payment is affordable for you, so set a sustainable amount after covering essentials and minimum payments. If you are undecided, a flexible format is less likely to box you into one strategy.
Is a paper debt payoff planner enough to keep my repayment plan accurate?
A paper planner can help you see account balances, due dates, and payment progress in one place, but you still need to verify details with each lender. Interest, fees, and payment posting dates can change the numbers written in your notebook. Set a regular time to compare your entries with current account statements or secure online accounts. Keep reminders in a calendar or banking app if a missed due date would create a problem. Treat the planner as a tracking and motivation tool, not as an automatic account feed or substitute for lender records.
What should I check if I have many debts to track?
Start by counting the accounts you want to include and noting how much detail you need for each one, such as balance, due date, interest rate, and payment history. Then check the planner’s dimensions, stated page count, and any available interior previews; a total page count alone does not reveal space per account. A larger format may be easier to write in, while a compact logbook may be easier to keep nearby. If the layout is unclear, avoid assuming it has dedicated pages for every debt. You can also keep a separate account list and use the planner for periodic progress updates.
Is a guided 12-week planner a good fit if I expect to take longer than 12 weeks to repay debt?
It can still help you organize an initial planning period, set routines, and review your budget, even if repayment will take longer. The time frame describes the guided sprint, not necessarily a promise that every balance will be cleared in that period. Check whether you can keep using its tracking pages after the initial schedule or whether you would need a new notebook for continued records. If you prefer a single ongoing log with no defined cycle, a simpler tracker may be a better match. Set milestones around your actual balances and affordable payments rather than treating the planner’s time frame as a deadline.
Should I get a larger notebook or a compact debt logbook?
Choose a larger notebook if you plan to write detailed notes, track several accounts, or use worksheets at a desk. A compact logbook may suit a short account list or a routine where portability and quick updates matter more than extra writing space. Neither size is automatically easier to use; the right choice depends on where you keep it and how often you write in it. Check the listed dimensions and look for interior examples before deciding, since page layout affects usable space. If you are unsure, think about whether you consistently use other notebooks of a similar size.
Conclusion
My best overall choice is The Debt Payoff Planner: A 12-Week Guided Sprint for readers who want method options plus budget and sinking-fund worksheets. For best value in practical tracking, I would start with a straightforward logbook such as the Debt Repayment Planner: Log Book Tracker; its stated 6-by-9-inch, 100-page format gives buyers concrete size and capacity details, though the interior layout should still be checked. The sprint planner is also my best premium-style pick for buyers who will use its added guidance, while the Simple Debt Tracking Log Book is my best for beginners who want a direct record-keeping starting point. For readers committed to the snowball method, choose the Snowball Debt Payoff Planner; for those who want more writing room, compare the 8.5″ x 11″ Financial Tracker Notebook and the larger 100-plus-page tracker. Match the planner to the habits you can sustain, then verify every balance and payment detail with your lenders.
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.